Just 1% allocation of life insurers’ assets could unlock INR 68,000 crore in domestic equity for India’s renewable energy sector: IEEFA
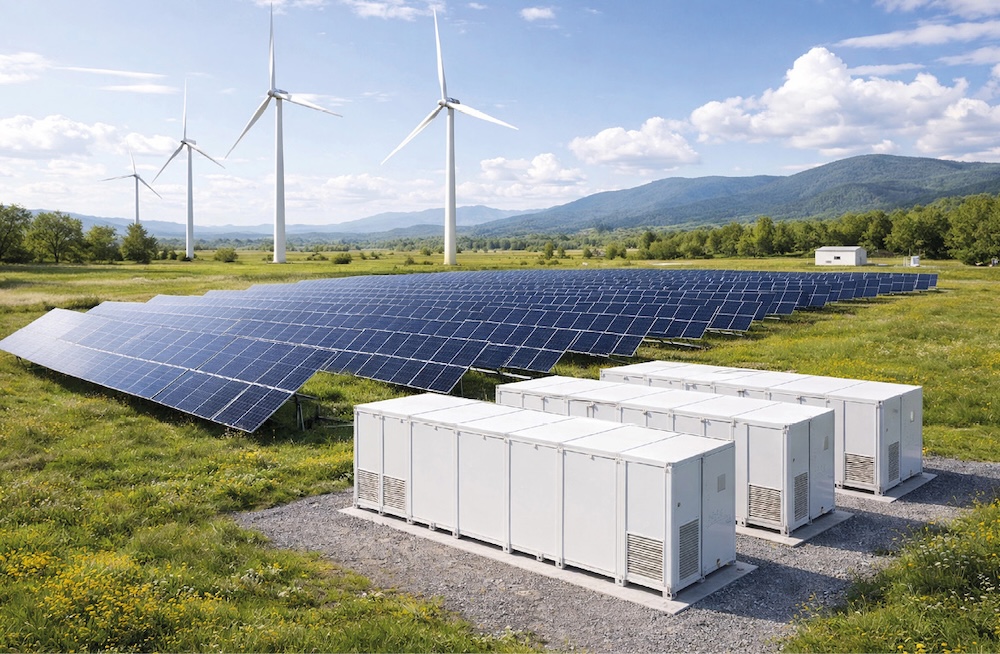
Growth equity for India’s unlisted renewable energy companies has come almost entirely from foreign investors so far. At the same time, domestic insurers and pension funds have largely stayed with listed companies and operating assets, according to a new report by the Institute for Energy Economics and Financial Analysis (IEEFA).
The report, titled ‘Mobilising domestic institutional capital in India’s clean energy transition’, proposes a phased approach, starting with domestic institutional investment in operational projects that generate established cash flows, followed by limited exposure to construction through structures that meet regulatory requirements and share early-stage risks.
While domestic financial institutions already lend to India’s renewable energy sector, equity participation by domestic institutional investors (DIIs) is concentrated in listed companies and operating assets.
Construction-stage growth equity has come predominantly from foreign investors. Broader domestic participation could diversify funding sources, reduce exposure to global investment cycles, and retain more of the development margin within India. This margin is the increase in an asset’s value as it moves from construction into operation, compensating investors for bearing construction risk.
“India’s life insurance companies had approximately INR 68 lakh crore ($717 billion) in assets under management as of March 31, 2025. An equity allocation of just 1% would amount to around INR 68,000 crore, illustrating the scale of the domestic capital pool. This is not a forecast or a recommended allocation. Mobilising any share of these funds would depend on investment structures meeting insurers’ regulatory requirements and risk limits,” says Shantanu Srivastava, Research Lead – Sustainable Finance, South Asia IEEFA, and lead author of the report.
Pension and provident funds represent additional pools of long-term capital, although their participation would depend on their respective investment rules and obligations to savers. The Employees’ Provident Fund Organisation (EPFO), for example, had an investment corpus of INR 28 lakh crore as of March 31, 2025, but can only invest in trusts sponsored by a public sector undertaking (PSU), which disqualifies any existing renewable energy equity vehicle.
To enable more DII investment, including from pension and provident funds, the first phase of the report’s proposed structure would channel DII investment into operational renewable energy projects through infrastructure investment trusts (InvITs). These trusts are investment vehicles which pool investors’ funds to hold infrastructure assets. Developers selling operating assets to these trusts could use the released capital to support new projects.
In the second phase, once an InvIT has sufficient scale and has established a track record to achieve a good credit rating, it could gain limited exposure to projects under construction through a separate platform. Developers would invest alongside other participants and remain responsible for project delivery.
“The report proposes transitional support from a public financial institution or multilateral organisation to absorb an initial layer of construction losses before the InvIT bears losses. This first-loss support would reduce, but not eliminate, investment risk,” says Tanya Rana, Energy Analyst, IEEFA, and co-author of the report.
Putting the proposed structure into practice would require investment instruments that meet investor-specific rules, clearly defined loss-sharing arrangements, and limits on construction exposure. Independent valuations would need to reflect project delays and underperformance, while exit arrangements would need realistic funding sources.
The report identifies three regulatory dependencies. These include a pending August 2026 proposal by the Securities and Exchange Board of India (SEBI) to allow InvITs to take minority stakes in third-party projects under construction, and extending tax pass-through treatment to interest received from entities outside the qualifying project-company structure. The National Bank for Financing Infrastructure and Development (NaBFID) would also need a mandate to provide the proposed capital that absorbs an initial layer of losses.
India already has most of the pieces in place, the report concludes. Recycling operating assets through InvITs is the first step, and a transitional public first-loss buffer could then extend domestic institutional capital to construction-stage equity.
This content is protected by copyright and may not be reused. If you want to cooperate with us and would like to reuse some of our content, please contact: [email protected].

Please login to comment